Subprime Auto Leads · Special Finance
Subprime Leads vs. Special Finance Leads: 4 Key Differences
Dealers often use the terms subprime leads and special finance leads interchangeably, but they are not the same. Each lead type represents a different buyer profile, different credit tiers, and different expectations for approvals and deal structure. Knowing the difference helps your dealership choose the leads that fit its lenders, its team, and its goals.
In short: subprime leads are strictly low‑credit buyers, while special finance leads cover a wider range that includes subprime, near‑prime, and first‑time buyers.
What are subprime auto leads?
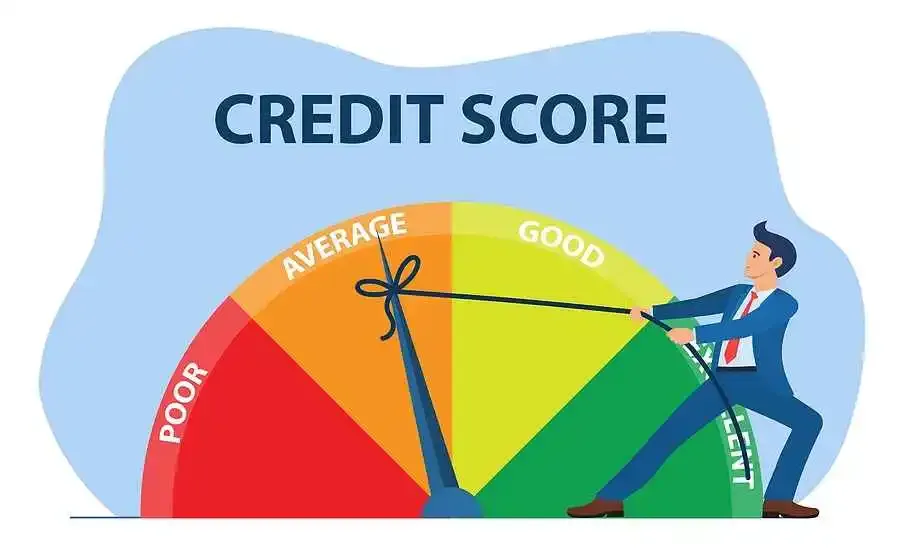
Subprime auto leads come from buyers with lower credit scores, typically in the 300–579 range (see Experian’s guide to credit score ranges). These consumers often have:
- Past repossessions
- High debt‑to‑income ratios
- Limited credit history
- Recent late payments
- A bankruptcy, open or discharged
Subprime buyers are usually actively looking for financing because they know approvals are harder to get.
Why dealers use them
- High demand for reliable transportation
- Strong motivation to buy
- Higher gross potential on subprime programs
- Lenders that specialize in credit‑challenged buyers
What you need to succeed
Subprime leads work best for dealerships with a true special finance department, or lenders who work heavily in the deep‑subprime space.
What are special finance leads?
Special finance leads cover a broader range of credit situations, including:
- Subprime (300–579)
- Near‑prime (580–669)
- First‑time buyers
- Thin credit files
- Moderate credit challenges
These buyers may not be deep subprime, but they still need non‑traditional financing. They are often comparison shopping and may qualify for more than one lender program.
Why dealers use them
- A larger pool of potential buyers
- Higher approval rates than deep subprime
- More flexible lender options
- Faster sales cycles
Best fit
Special finance leads are ideal for dealerships that want volume without the complexity of deep‑subprime underwriting.
4 key differences at a glance
1. Credit tier range
- Subprime: strictly low‑credit buyers (300–579)
- Special finance: subprime plus near‑prime and limited‑credit buyers
2. Approval difficulty
- Subprime: harder approvals, more documentation
- Special finance: easier approvals, more lender flexibility
3. Buyer motivation
- Subprime: highly motivated, often urgent
- Special finance: motivated but more selective
4. Deal structure
- Subprime: higher rates, shorter terms, lender stipulations
- Special finance: more standard terms, more lender options
Which lead type does your dealership need?
Choose subprime leads if
- You have a strong special finance department
- You work with deep‑subprime lenders
- You want higher‑gross deals
- You can handle more complex approvals
Choose special finance leads if
- You want higher volume
- You want easier approvals
- You serve a wide range of credit profiles
- You want faster sales cycles
Tip: most dealerships benefit from a mix of both. The right balance depends on your lender lineup and your sales strategy.
Final thoughts on subprime vs. special finance leads
Both lead types help dealerships reach credit‑challenged buyers, but they serve different purposes. Subprime leads deliver highly motivated buyers with lower credit scores, while special finance leads offer a broader range of credit profiles and easier approvals. Whichever you choose, verified leads keep your team focused on real, reachable buyers.
Whether you are targeting deep‑subprime buyers or building a broader special finance pipeline, we deliver verified leads backed by real buyer intent.
Subprime and special finance lead FAQs
What credit score counts as subprime?
Subprime buyers typically have credit scores in the 300–579 range. Near‑prime buyers usually fall between 580 and 669.
Are special finance leads the same as subprime leads?
No. Special finance leads include subprime buyers, but they also cover near‑prime, first‑time, and thin‑file buyers.
Which lead type is easier to get approved?
Special finance leads usually see easier approvals because many of those buyers qualify for more lender programs.
Can my dealership use both lead types?
Yes. Many dealerships use a mix, adjusting the balance to fit their lenders and sales team.
How much do the leads cost?
Pricing depends on your market and the program that fits your dealership. Call us at 1-800-793-1087 to talk with a VP Marketing specialist.
Not sure which leads fit your dealership?
Talk with a VP Marketing specialist about the right mix of subprime and special finance leads for your market.